

Upgrade
by Upgrade, Inc.
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
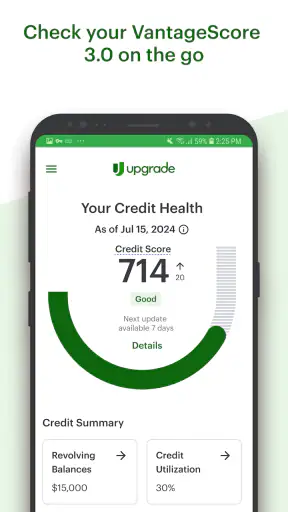
 Analysis by Getfullapps
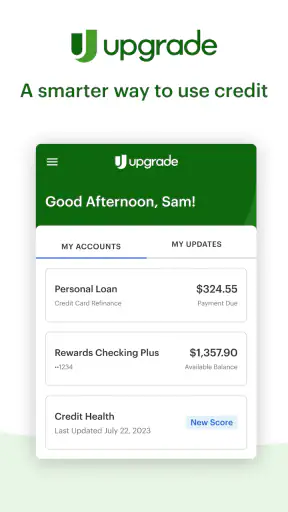
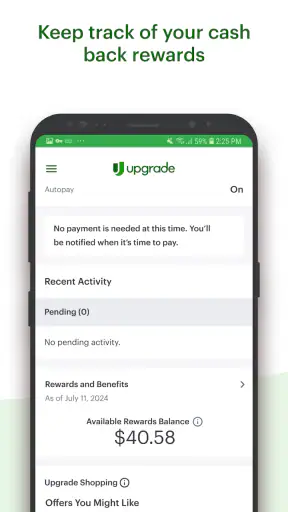
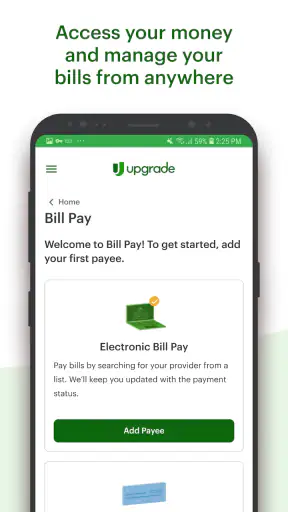
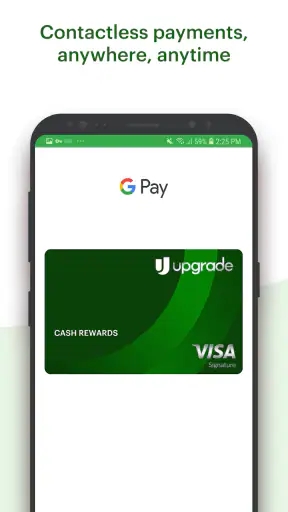
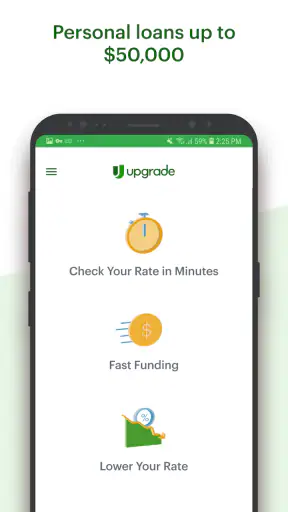
When money is spread across a card, a checking account, and a loan application, the difficult part is often not spending itself but keeping the whole picture together. I found Upgrade most useful in that situation: it brings personal loans, cards, and rewards checking into one finance-focused app from Upgrade, Inc. The approach is more practical than flashy. It is designed for someone who wants to review borrowing and everyday money tools in one place rather than jump between unrelated financial apps.
The app is free to download and is rated for Everyone, which makes it approachable for ordinary household use. It has passed the one-million-install mark and holds a 4.4 average from roughly thirty thousand ratings, with about three thousand eight hundred written reviews. Those figures suggest a product that has reached a substantial audience, but they do not remove the need to judge whether its particular combination of services fits your habits.
From a money problem to a usable routine
I would start with Upgrade when I had a clear financial task, such as exploring a personal loan, managing an Upgrade card, or looking for a checking account with rewards. That starting condition matters. This is not an app I would open simply to watch every account from every bank in one universal dashboard. Its value comes from the products connected to the Upgrade experience, so the first question is whether one of those products matches the problem I am trying to solve.
A realistic example is a household facing a large repair bill. The person may need to understand whether a personal loan is appropriate, while also wanting a card for regular purchases and a checking option for day-to-day money. Instead of treating those as completely separate searches, the app gives that person a single place to begin comparing the available Upgrade paths. I like that starting point because it encourages a more complete decision, although it also means the app is less useful to someone who only wants a basic spending tracker.
The first practical step is to decide which part of the service deserves attention. Someone considering borrowing should concentrate on repayment details and affordability, not on the convenience of seeing other products nearby. Someone interested in checking should focus on how the account would fit an existing banking routine. A card user, meanwhile, should think about whether the card’s structure suits the way they already pay bills and everyday expenses. Keeping those questions separate prevents the combined interface from turning one financial need into several unnecessary decisions.
In my experience, this is where a little preparation saves time. Before moving through an application or product screen, I would write down the purpose of the money, the amount I can comfortably handle, and the payment date that would be easiest to maintain. That small workflow is especially important for a loan because a smooth digital application can make borrowing feel simpler than the underlying commitment really is. The app can organize a decision, but it should not make the decision for you.
Moving through the app without losing the purpose
Once I know what I am trying to accomplish, the app’s three-part structure becomes easier to understand. Personal loans address a borrowing need, cards connect spending with the Upgrade account experience, and rewards checking is aimed at everyday banking. The products sit close together, but I would not treat them as interchangeable. Each one creates a different handoff: from an initial need to an application, from an approved product to regular use, or from a financial goal to a recurring money routine.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
For a loan workflow, I would begin by reviewing the purpose and the repayment implications before thinking about speed or convenience. The useful outcome is not merely reaching an application screen; it is knowing what monthly obligation I am willing to accept and what would happen to my budget after the money arrives. The app is a helpful starting point for that process, but responsible comparison still requires reading the terms presented during the application carefully.
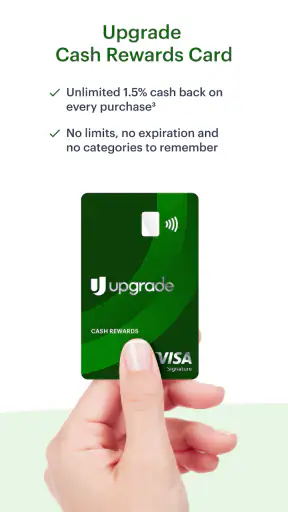
For the card, the workflow is different. I would first consider which purchases belong on it and how I plan to clear the balance. A card can be convenient for regular spending, but convenience becomes a weakness if it encourages spending without a repayment plan. I found the combined design helpful for keeping the card in the same mental space as other Upgrade services, yet that convenience can also tempt users to explore more products than they originally needed.
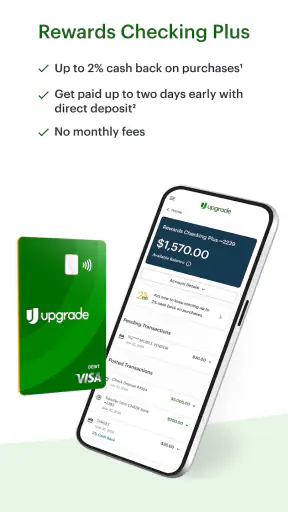
Rewards checking works best when it becomes part of a routine rather than a feature I occasionally inspect. I would use it as the destination for money that needs a clear job: regular household spending, planned bills, or a defined savings-related workflow. The practical tip here is to decide in advance which payments belong there. If the account is added without changing how bills and spending are organized, the result may be another balance to monitor instead of a simpler financial system.
The current version is 1.33.0, and the app requires at least iOS or Android version 12. That operating-system requirement is worth checking before planning a move to the service, especially if the phone is older or has not been updated recently. The app is free, but financial products inside an app should never be judged only by the download cost. The meaningful questions are the terms, obligations, eligibility, and everyday fit of the product selected.
Where the handoffs happen
The most important part of this experience is the handoff between information and action. A user may arrive looking for a loan, then notice the card and checking options. That transition can be useful if it reveals a more suitable way to handle the original need. For example, a recurring spending problem might be better addressed by reorganizing the checking routine than by borrowing. On the other hand, moving from one product screen to another can blur the original goal if the user is not careful.
I recommend treating every handoff as a pause point. Before moving from a loan discussion to a card, I would ask whether the new product solves the same problem or introduces a different obligation. Before adding checking to an existing setup, I would identify which account will receive income, which one will pay bills, and how transfers will be handled. This makes the app’s broader ecosystem work for me rather than allowing the product menu to dictate my financial plan.
There is also a handoff between the app and the user’s wider financial life. Upgrade can present a focused route, but it does not replace checking statements, reviewing a household budget, or comparing alternatives outside the service. I would still keep a separate record of recurring commitments and review the final terms before accepting anything. That may sound cautious, but it is the difference between using the app as a decision tool and treating it as an automatic answer.
Compared with a traditional bank app, Upgrade feels more centered on connecting lending, card use, and checking around one provider. A conventional bank may offer a broader range of accounts or a longer-established branch relationship, which can be better for someone who wants all financial needs handled through a familiar institution. Compared with a standalone budgeting app, Upgrade is less about importing and categorizing every account and more about using its own financial products together. That distinction is important: users seeking detailed whole-market tracking may prefer a dedicated budgeting service, while users considering an Upgrade product may appreciate the tighter workflow here.
What the completed workflow feels like
The best result is a clearer path from a specific need to a manageable money arrangement. In the repair-bill example, that might mean understanding whether a personal loan belongs in the budget, using a card only for planned purchases, and placing everyday cash flow in a checking setup that is easy to monitor. The app’s strength is the continuity between those stages. I do not have to begin from an entirely different financial context each time I examine one of the connected services.
That continuity is also useful for people who dislike administrative clutter. If I were helping a friend organize a new financial routine, I could see the appeal of having the loan, card, and checking conversation start from the same app. The workflow is easier to remember than a collection of disconnected services, and the free entry point makes it simple to explore the interface before deciding whether it belongs in a longer-term routine.
Still, the result depends heavily on discipline. A single app does not automatically create a single financial plan. I would set a regular review habit, check upcoming obligations, and avoid interpreting rewards or convenience as a reason to spend more. One non-obvious benefit of the combined setup is that it can expose a mismatch between borrowing and everyday cash flow: if a loan payment would make ordinary checking activity uncomfortable, that is valuable information to notice before proceeding.
Another useful workflow is to use the app as a staging area before making a change elsewhere. I might review the product I am considering, write down the questions it raises, and only then decide whether to move money or apply. This reduces impulsive decisions and gives me a chance to compare the Upgrade route with my current bank. It also answers a common concern: downloading the app does not mean I need to adopt every product it presents.
Where the flow breaks down
The biggest friction is the same feature that makes Upgrade appealing: the products are presented together. For a focused user, that is convenient. For someone already uncertain about borrowing or credit, it can create too many nearby choices. I would skip the app if I wanted a neutral marketplace covering many providers, because the experience is naturally organized around Upgrade, Inc. rather than around every possible alternative.
I would also hesitate to rely on it as my only financial tool if I need deep budgeting across several institutions. The app’s purpose is more specific than a full financial-aggregation service. A person with investments, multiple banks, shared household accounts, or complicated income may need a broader system for seeing everything together. In that case, Upgrade could still serve one product, but it would not necessarily replace the wider financial setup.
Loan applicants should be especially careful about confusing a straightforward interface with a straightforward commitment. I would read every repayment detail, consider how the payment fits alongside rent and essential bills, and avoid applying merely because the process feels accessible. The same caution applies to the card: it is a poor fit for someone who is trying to eliminate revolving debt but does not yet have a reliable repayment routine.
There are smaller practical questions a new user should settle before switching. Can the app run on the phone’s operating system? Which existing account will remain the main source for bills? Will the new checking arrangement simplify deposits and payments or merely add another place to look? What is the exact reason for choosing a loan, card, or checking product? Answering those questions first makes the onboarding process more purposeful and reduces the chance of abandoning a half-finished setup.
The app’s age rating of Everyone makes sense for its general presentation, but financial suitability is a separate issue. An interface can be accessible while the products still require adult judgment about income, repayment, and spending. I would recommend it to someone who wants a guided way to explore Upgrade’s connected financial services and is willing to read the details carefully. I would not recommend it as a casual download for someone who is only browsing or hoping for an all-in-one replacement for every banking and budgeting tool.
After using it as a complete workflow rather than as a collection of buttons, I see Upgrade as a focused finance app with a clear practical audience. Its strongest point is the handoff from personal loans to cards and rewards checking, allowing a user to consider borrowing and everyday money management in one environment. Its main weakness is that this focus can narrow comparison and encourage product exploration beyond the original need.
My recommendation is straightforward: try it when you have a defined reason to examine an Upgrade loan, card, or checking account, and keep your own budget beside the app while you do it. If that combination matches your situation, the free app can make the next steps feel organized and less scattered. If you need independent comparisons, detailed tracking across many providers, or a simple spending ledger with no product decisions attached, a traditional bank app or dedicated budgeting tool may be the better choice.
For me, the deciding test is whether the app produces a better outcome after the handoffs, not whether it makes the first screen look convenient. Used carefully, Upgrade is most valuable as a focused route from a defined money problem to a more organized financial routine. Used without a clear purpose, it risks becoming another place to browse rather than a tool that genuinely improves how money is handled.
Pros
- Simple upgrade process with clear steps and minimal setup.
- Can unlock useful features without requiring advanced technical knowledge.
- Improves access to the latest app tools and performance updates.
- Upgrade options are easy to find within the app interface.
- Suitable for users who want a more complete app experience.
Cons
- Some upgrades may require payment or a recurring subscription.
- Benefits can vary depending on the device and operating system.
- The app may use more storage after certain upgrades.
- New features could take time to learn after upgrading.
- Downgrading to an earlier version may not be straightforward.
FAQs for Upgrade
What is Upgrade, and what can I use it for?
Upgrade is a financial app designed to help users manage personal finances through products and tools such as a checking account, debit card, personal loans, credit monitoring, and budgeting features, depending on eligibility and location. After installing it, you can review available services, monitor account activity, and manage payments from one place. Features may vary by state, account type, and approval status.
Is Upgrade free to download and use?
The Upgrade app is generally free to download, and there is usually no charge simply for creating an account or browsing its features. However, some financial products may include interest, origination fees, late-payment fees, ATM charges, or other costs. Before accepting a loan or using a specific account feature, carefully review the terms, pricing, and fee information shown in the app.
Can I apply for an Upgrade personal loan through the app?
Yes, eligible users can typically check personal-loan offers through the Upgrade app. The application normally requires identity, income, employment, and other financial information, and approval is not guaranteed. Checking available offers may involve a soft credit inquiry, while accepting an offer can result in a hard inquiry. Read the annual percentage rate, repayment period, fees, and total repayment amount before proceeding.
Is Upgrade safe for managing money and personal information?
Upgrade uses standard security practices intended to protect account information, including encrypted connections, identity verification, login safeguards, and transaction monitoring. Nevertheless, no financial service is completely immune to fraud or unauthorized access. Use a strong, unique password, enable available security features, avoid sharing verification codes, and contact official support immediately if you notice unfamiliar transactions or suspicious activity.
What should I know before downloading and opening an Upgrade account?
Before downloading Upgrade, confirm that the service is available in your country or state and that your device meets the app’s requirements. You may need to provide government identification, a Social Security number or equivalent information, income details, and bank-account data for verification. Also check the latest privacy policy, product disclosures, eligibility rules, and customer-support options, since terms and available features can change.

Upgrade
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via mobile_app_feedback@upgrade.com, visit http://www.upgrade.com, or review their https://www.upgrade.com/privacy.










